Your Freedom Number is the monthly income from property, before tax, that would make work a choice, not a need. Choose yours, put in your money, and see how many homes and how many years it could take. An illustration only.
Put in your money, press play, and see how many homes £100,000 could buy you over 10 years, and what they could pay you every month. An illustration only.
An illustration only, not a forecast or a promise. Monthly figures are rent after mortgage interest and running costs, before tax.
Money released by refinancing is borrowed and must be repaid.
Book a Clarity Call and we will show you how your own numbers could work.
Book a Clarity CallFree call with our team.This simulator is an illustration only. It is not a forecast, a guarantee or financial advice, and your own results could be higher or lower. It uses typical North East or North West prices and rents, as chosen above. Buying below market value depends on each deal and is never guaranteed. Refinancing depends on lenders, valuations and interest rates at the time, and money released by refinancing is a larger mortgage that must be repaid. Monthly figures are rent after mortgage interest and running costs, before corporation tax and personal tax. Running costs allow for management, repairs, insurance, certificates and empty months, but real costs vary. Figures do not allow for changes in interest rates. Property values can fall as well as rise. Past performance is not a guide to future results. Please take independent advice before investing.
When I first met my wife, she lived in London and I lived in Suffolk. I would travel as often as I could to see her, and the road that connected us was the A505 past Royston. I remember making that journey with excitement and anticipation every time, which is very similar to the excitement you feel investing in property for the first time.
My wife and I started this company together, and I wanted the name to be meaningful to both of us. So we chose Property505.
Then, when I googled the number 505, I found this wonderful response:
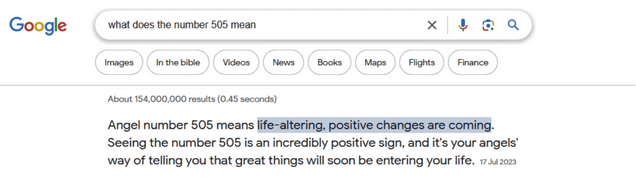
The mission of Property505 is echoed in these exact words, as this is what our services do for our clients. We change their lives for the better. I couldn’t have hoped for a more perfect fit, and so the name Property505 was born.
Yes, you will typically have an interest only Buy-to-Let mortgage to the value of 75% of the value of the property.
Why interest only you may ask? Because you want to maximise your cash flow and therefore paying off the principal isn’t in your best interests. You will also want to remortgage in 5-6 years and release the equity that has built up over time so that you can buy more properties. If you are going to release equity in the future anyway it makes little sense to reduce your cash flow in the short term.
At the end of the program, you will own the property through a limited company.
Please note that I am not a licensed financial advisor or accountant, and I always recommend seeking professional advice when considering the tax implications of owning property.
Owning property through a limited company is widely accepted to be the most tax-efficient method. This is because you are exempt from Section 24 tax, which affects private landlords. Section 24 tax means that private landlords are taxed on the full rental income of the properties they own, without being able to offset their mortgage payments as deductible expenses.
For example, if you rent out a property for £1,000 per month and your mortgage is £500 per month, you will pay tax on the full £1,000 income as a private landlord. However, if you own the property through a limited company, you will only pay tax on the profits, which is £500 per month less insurances and fees.
Another significant advantage of owning property through a limited company arises when you have additional income that pushes you into a higher tax bracket. If you hold the property in your own name and you’re already earning more than £50,000/year, you’ll be subject to higher income tax rates (40% or 45%) on your rental income. However, with a limited company, you only pay corporation tax, which starts at a lower rate of 19% of profits.
We Respect Your Privacy. Your Information Will Never Be Shared
We Respect Your Privacy. Your Information Will Never Be Shared
We Respect Your Privacy. Your Information Will Never Be Shared
We Respect Your Privacy. Your Information Will Never Be Shared